NBS Introduces Temporary Foreign-Exchange Rules
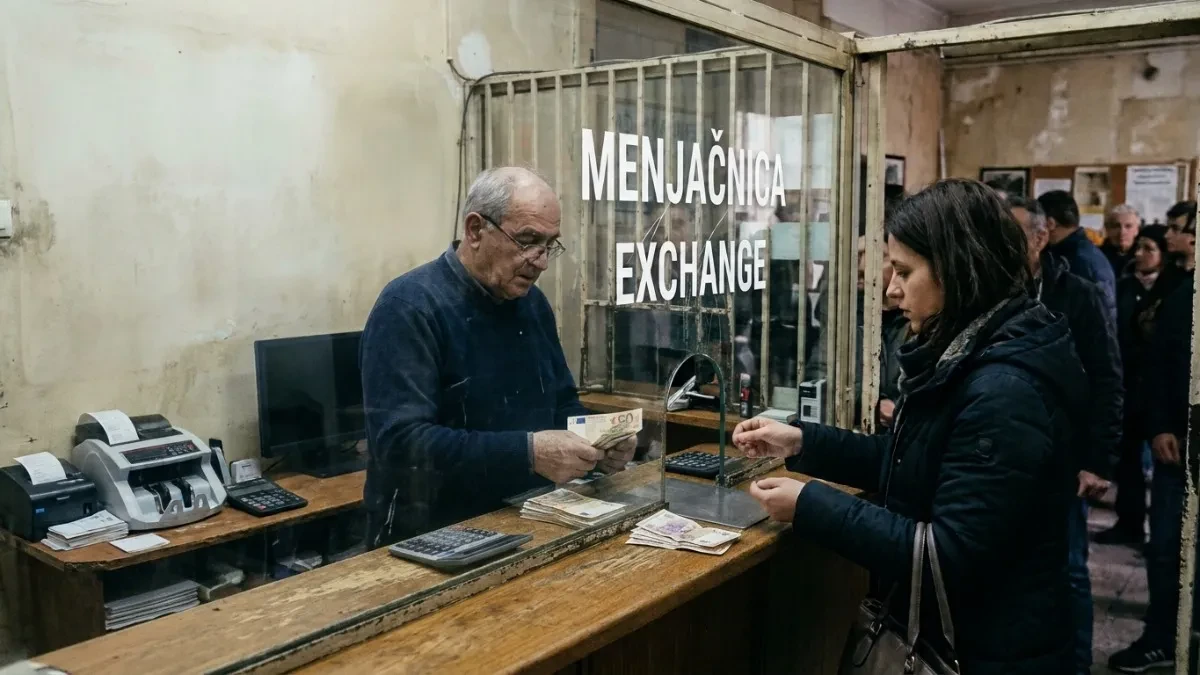
NBS Introduces Temporary Foreign-Exchange Rules
The National Bank of Serbia has introduced temporary changes to foreign-exchange trading rules that affect exchange offices, public postal operators, and banks across the country. According to aligned accounts, the measures set concrete deadlines—most often described as 30‑day and 60‑day windows—for selling foreign cash and non-cash foreign currency that these entities purchase from clients on the domestic market to banks. Reports concur that exchange offices will now be obliged to sell a fixed share, typically cited as 50 percent, of their net purchased foreign currency to banks on at least a weekly basis. The rules are clearly presented as temporary, with most outlets noting that some provisions apply until January 15, 2027, while others are only in force until January 15 of the following year, and they are framed as having already entered into effect as of mid‑November.
Coverage from both sides also agrees that the NBS remains the central institutional actor driving these changes, using its regulatory authority over the foreign-exchange market to intervene in the behavior of licensed exchange offices and public postal operators. While opposition and pro-government outlets differ on interpretation, they both situate the move within broader concerns over foreign currency availability, exchange rate stability, and the functioning of the dinar–euro segment of the market. Both camps describe the rules as part of a pattern of NBS and government responses to pressures on the currency and foreign-exchange market, referencing prior measures aimed at curbing speculative behavior and ensuring sufficient foreign-cash circulation through the banking system. There is also shared acknowledgment that these are not structural liberalization reforms but rather targeted, time-limited administrative constraints meant to steer liquidity flows until market conditions are judged more stable.
Areas of disagreement
Motives and problem diagnosis. Opposition-aligned sources typically portray the new rules as an emergency reaction to deepening foreign-exchange imbalances, suggesting that the NBS is scrambling to contain a shortage of euros and underlying pressures on the dinar. They emphasize that forcing exchange offices to offload half of their net purchases and imposing strict deadlines signals a system that cannot rely on normal market functioning. Pro-government coverage, by contrast, presents the same measures as a prudent, pre-emptive step to maintain order and transparency in the FX market, stressing continuity with past policy and denying that there is any fundamental currency or liquidity crisis.
Impact on market actors and citizens. Opposition narratives tend to stress potential negative consequences for small exchange offices, arguing that mandatory weekly sales to banks and rigid deadlines could squeeze their margins, reduce competition, and ultimately worsen rates for ordinary citizens. They frame the policy as shifting the burden of macroeconomic management onto small businesses and consumers, predicting tighter access to cash euros outside the banking sector. Pro-government outlets instead underscore that the rules will ensure better availability of foreign cash through banks, stabilize spreads, and protect citizens from speculative behavior at unregulated or semi-regulated counters, minimizing mention of any costs for exchange offices themselves.
Assessment of NBS credibility and transparency. Opposition media often use the decision to question NBS communication and independence, claiming that the central bank is downplaying the seriousness of FX pressures and withholding data on interventions or market shortages. They link the rules to broader accusations of politicization of monetary policy and opacity in how reserves are managed. Pro-government reporting, however, highlights the NBS as a competent, technocratic institution acting within its legal mandate, presenting the detailed timeframes and percentages in the decision as evidence of transparency and rule-based policy rather than ad hoc improvisation.
Political framing and broader economic outlook. Opposition coverage tends to situate the FX rules within a narrative of broader economic vulnerability, connecting them to concerns about inflation, public debt, and election-cycle spending, and alleging that the government is masking structural weaknesses with short-term controls. They argue that frequent temporary measures signal uncertainty and undermine investor confidence. Pro-government sources frame the same steps as consistent with a generally stable macroeconomic environment, citing maintained dinar stability and adequate reserves, and they characterize the time-limited nature of the rules as proof that authorities expect conditions to normalize rather than deteriorate.
In summary, opposition coverage tends to interpret the temporary FX rules as a symptom of deeper currency and market stress, questioning NBS credibility and warning of negative impacts on competition and citizens, while pro-government coverage tends to frame them as a measured, technical intervention that protects market stability, reassures the public, and confirms the soundness of Serbia’s broader economic management.
Write a comment