Buying Off-Plan at Sukoon by Nuri Without Legal Surprises
- The reservation form is not the contract
- Escrow is the only real protection on your 30%
- Documents that must exist at handover
- Bookkeeping for individual and corporate owners
- Where this purchase stops making sense
- Questions buyers ask before signing
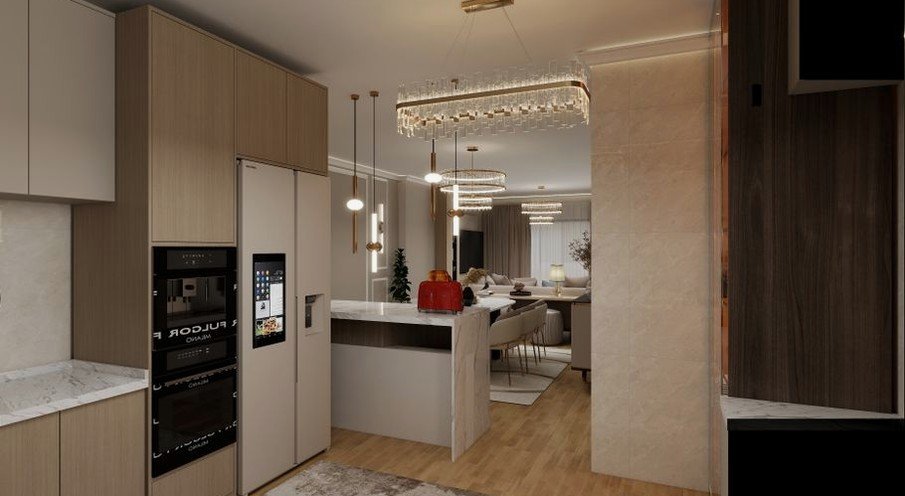
Sukoon by Nuri is a 38-unit boutique off-plan building in Nad Al Sheba 1, Dubai, developed by Nuri Living. The mix runs from one- and two-bedroom apartments to three-bedroom penthouses, with living areas between 778 and 5,062 sq ft and a starting price of AED 1,500,000. The payment structure is 30/70: 10% down, 20% during construction, 70% at handover in Q4 2026. The legal and accounting mechanics below decide whether that schedule stays comfortable or turns into a cash-flow problem.
The reservation form is not the contract
A booking form holds a specific unit for a short window and usually states the price and the payment plan. It does not transfer ownership, and it rarely protects you if the developer changes the specification. The binding document is the sale and purchase agreement, which should be read line by line before the second installment, not after.
Four clauses carry most of the risk. The unit description must state the number, the floor, the internal area in square feet and the terrace area separately, because price per sq ft on a 5,062 sq ft penthouse swings heavily depending on what is counted. The payment schedule must tie each installment to a construction milestone rather than to a calendar date. The delay clause should specify what the developer owes you if handover slips past Q4 2026. The specification annex should list finishes, since the interiors by Bergman Design House and the renders in the brochure are marketing material, not a contractual obligation.
Register the signed agreement with the Dubai Land Department through the Oqood system. An unregistered contract is a private promise between you and Nuri Living; a registered one is a recorded interest that survives a resale of the project or a change in developer structure. The project page at nadalshebadubai.ae lists the current unit types and price points, which is useful for cross-checking the figures written into your agreement.
Escrow is the only real protection on your 30%
Off-plan payments in Dubai belong in a project-specific escrow account, and construction installments are released against verified progress. The practical test is simple: the account name on the invoice should match the registered project, not a general developer account. Ask for the escrow account number and the project registration number in writing before the first transfer, and keep every bank confirmation.
If a buyer wires the 10% down payment to a corporate account “for speed,” the money leaves the protected structure and the recovery path becomes a lawsuit. This is the single most common expensive mistake in off-plan purchases, and it takes one email to avoid.
Documents that must exist at handover
Before the final 70% leaves your account, you should hold a snagging report with a signed punch list, the developer’s completion notice, a handover certificate, and the utilities connection in your name. The title deed follows registration at the Land Department after final settlement; until then, the Oqood record is your proof of ownership.
Ask for the service charge budget at the same time. A boutique building with a pool, gym, landscaped grounds and 24/7 security spreads fixed costs across only 38 units, so per-square-foot charges on the largest penthouse will be the dominant recurring expense, well above what a 300-unit tower charges. Model that number before you compare the 6-7% average ROI figure against anything else.
Bookkeeping for individual and corporate owners
An individual buyer needs a single file: the registered agreement, escrow receipts for each installment, the title deed, service charge invoices and, once rented, the tenancy registration and rent receipts. That file is what an accountant or a bank asks for when you refinance or sell.
A company holding the unit treats it differently. Off-plan installments are normally capitalized as an asset under construction rather than expensed. The unit moves to investment property at handover, and rental income and service charges sit on separate lines. Because the dirham is pegged to the dollar, USD reporting is quiet; euro or ruble reporting introduces revaluation noise that has nothing to do with the property’s actual performance.
Where this purchase stops making sense
Thirty-eight units means thin secondary market liquidity. If you need to exit in a hurry, you are negotiating with a small pool of buyers who could equally buy directly from Nuri Living. The quoted ROI of 6-7% average and up to 8-9% is a projection, gross of service charges, vacancy and management, so treat it as a ceiling rather than an expectation.
Off-plan also means the 70% falls due in one lump at Q4 2026. Buyers who plan to fund that with a mortgage should confirm financing early, because a delayed valuation at handover is a cash problem, not a paperwork problem. Anyone needing rental income this year should look at ready stock instead.
Questions buyers ask before signing
Is the 30/70 plan a payment scheme or a mortgage?
It is a payment scheme. The developer splits the price into 10% down, 20% during construction and 70% at handover. No bank is involved unless you arrange separate financing for the final installment.
Do I own the unit before handover?
You hold a registered contractual interest through Oqood. Full ownership is recorded as a title deed at the Land Department after the final payment and handover formalities are complete.
Can a company buy instead of an individual?
Yes. Corporate ownership changes the accounting treatment, the reporting obligations and the tax position, so confirm the structure with an accountant before the reservation form is signed.
Is the advertised ROI guaranteed?
No. The 6-7% average and 8-9% maximum are developer projections based on assumed rents and occupancy, calculated before service charges, management fees and void periods.
- Reference: https://nadalshebadubai.ae/sukoon-by-nuri/
Write a comment