Banco Master’s safety net protected small savers, but the losses still have no clear home
Banco Master’s safety net protected small savers, but the losses still have no clear home
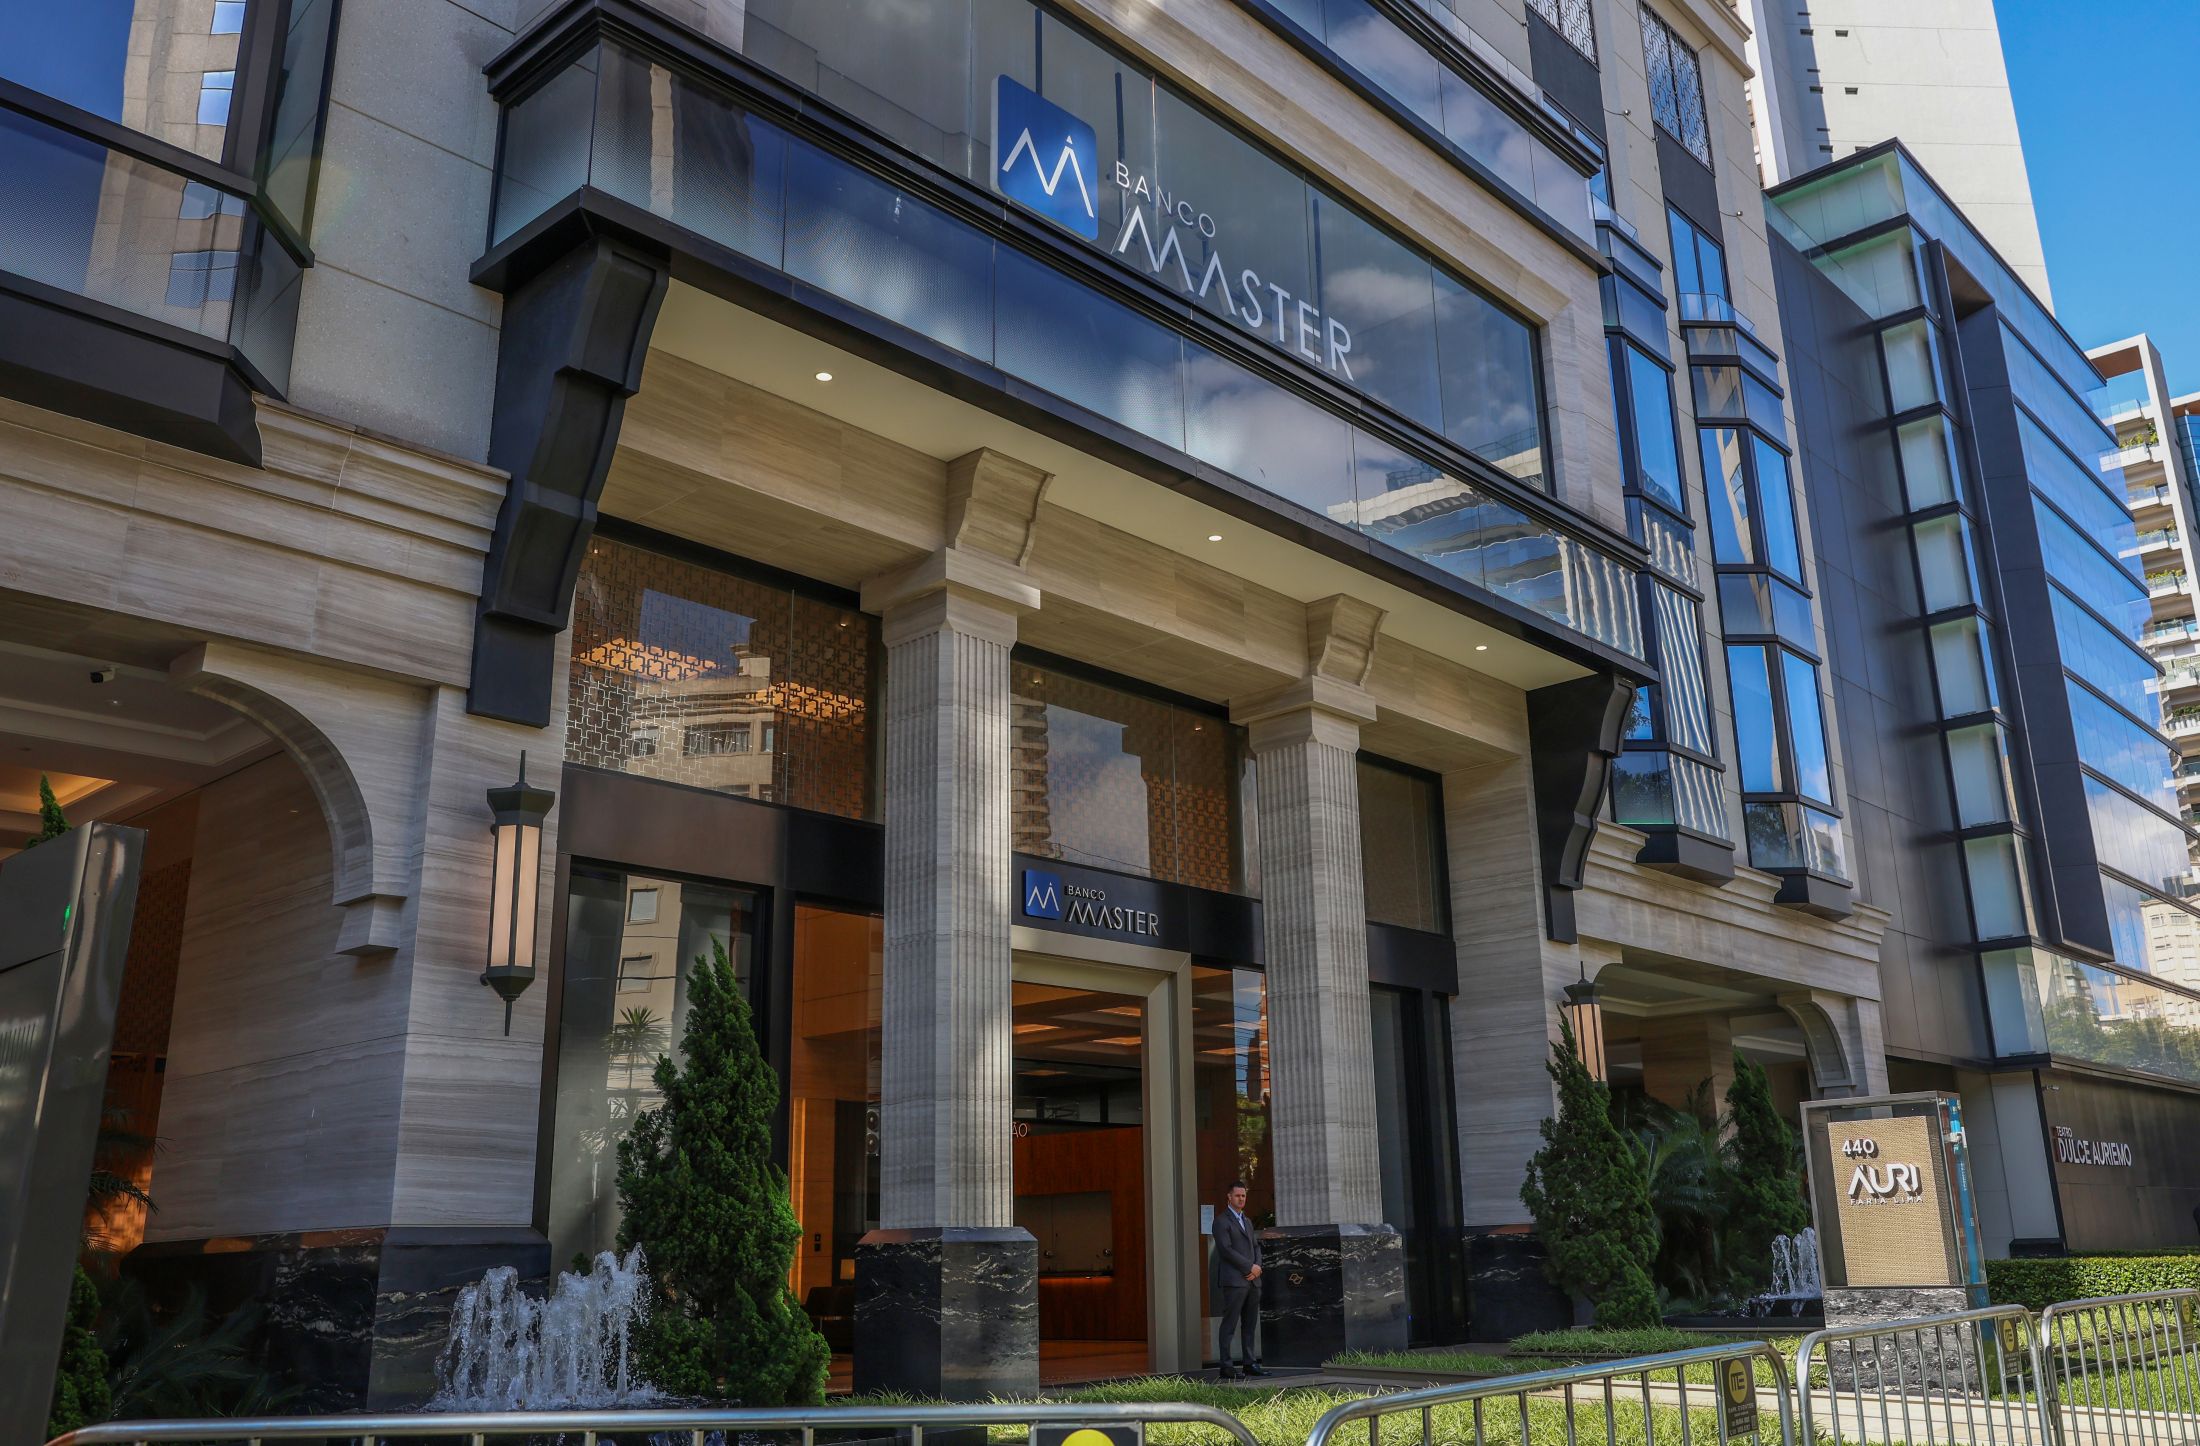
One year after Banco Master’s liquidation, the contrast is stark: the financial safety net has reimbursed most smaller depositors, but the largest unresolved exposures sit with public bodies, pension regimes and creditors outside that protection.
The Fundo Garantidor de Créditos (FGC) had paid about R$40.03 billion to 722,000 investors by July 2026, covering roughly 93% of eligible claims up to its R$250,000 limit. Yet creditors above that threshold, as well as holders of uncovered instruments, still depend on the liquidation process and the sale of difficult-to-monetize assets. Restructuring specialist Salvatore Milanese warned that “an important part” of investors will not be repaid and said a full recovery could take a long time.
The public-sector exposure gives the case a different dimension. Federal Police investigators have identified at least R$2.7 billion in losses tied to transactions between Banco Master and the state-controlled Banco de Brasília (BRB), while the Central Bank has estimated BRB’s potential losses could reach R$11.4 billion when other assets are included. BRB says it has recovered or replaced more than R$10 billion in assets and is pursuing legal action, but it may still require capital support from the Federal District government.
Pension funds face a parallel risk. Their exposure to Master-linked investments reached R$4.49 billion, led by Rioprevidência’s identified R$3.69 billion exposure. Unlike insured deposits, the financial letters held by these funds are not protected by the FGC; if recoveries fall short, state and municipal governments may have to cover pension deficits from their own budgets.
Critics such as Milanese argue that supervisors, external auditors and rating agencies should have detected the bank’s reliance on illiquid and high-risk assets earlier. Others take a less alarmed view: Insper professor Alexandre Chaia says the system absorbed the failure without a bank run and that stronger rules now represent a regulatory reset. The dispute, then, is between a view of lasting socialized costs and one of a painful but contained correction.
https://brazil-test-hub.syndichain.com Brazil News Hub brazil-test-hub brazil-test-hub
Write a comment